
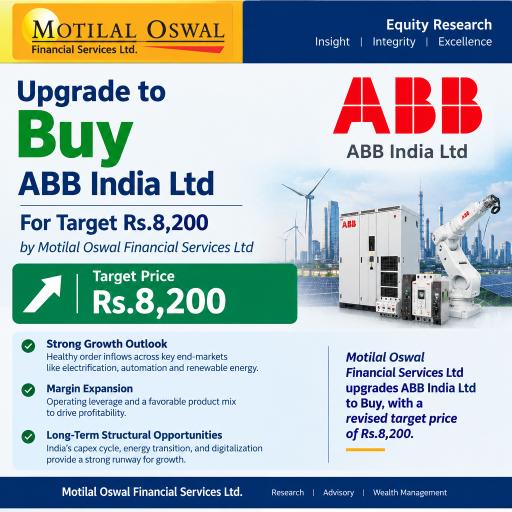
Upgrade to Buy ABB India Ltd For Target Rs.8,200 by Motilal Oswal Financial Services Ltd
ABB India’s third-quarter CY26 performance reinforced expectations of faster growth and a gradual recovery in profitability. Strong demand from data centres, utilities, metals, mining, food and beverage, cement, and infrastructure helped lift quarterly order inflows by 56% year on year to Rs.47.3 billion.
The order backlog expanded 36% to Rs.129 billion, giving the industrial technology company improved revenue visibility for the coming quarters. Against this backdrop, the stock rating has been raised from Neutral to Buy, with a revised target price of Rs.8,200.
Revenue meets expectations as profitability improves
Excluding the Robotics business, quarterly revenue increased 19% year on year to Rs.37.4 billion. Most operating divisions recorded growth, although Industrial Automation remained subdued.
Gross margin stood at 37.1%, while earnings before interest, tax, depreciation and amortisation rose 14% to Rs.5.5 billion. The EBITDA margin reached 14.8%, exceeding expectations due mainly to stronger profitability in Electrification. Adjusted profit after tax advanced 10% to Rs.4.4 billion.
For the first nine months of CY26, revenue grew 15%. EBITDA and adjusted profit declined 3% and 5%, respectively, while the EBITDA margin narrowed by 250 basis points to 13.4%. The year-on-year pressure reflected elevated commodity and logistics expenses, currency movements, competitive pricing and weaker volumes in selected operations.
Electrification benefits from energy-transition spending
Electrification continues to be a major growth engine. Orders in the division climbed 72% during the first nine months of CY26, accompanied by a 29% increase in revenue. Demand is being supported by grid upgrades, renewable energy integration, expanding data-centre capacity and the need for more efficient power distribution across industrial and commercial facilities.
These trends position ABB India to participate in the broader shift towards lower-carbon electricity systems. Equipment for grid modernisation, energy management and industrial electrification is increasingly important as renewable generation expands and businesses seek to reduce energy consumption.
Earlier price increases are also beginning to flow through to results. Combined with stronger execution and a larger backlog, they should support continued growth in the Electrification division.
Motion division shows signs of acceleration
Excluding Robotics, orders for the Motion business rose 21% year on year during the nine-month period. The division supplies motors, drives and related technologies that can improve industrial efficiency and reduce electricity use.
Demand from private capital expenditure, railways and services is expected to support a recovery. Revenue growth in Motion could reach approximately 16% to 18% as pricing improves and customers invest in automation and energy-efficient equipment.
Industrial Automation, however, may need more time to regain momentum because both orders and revenue remain relatively soft.
Margins recover sequentially
Although divisional operating margins remained below year-earlier levels, the quarter showed a meaningful sequential improvement. Electrification’s EBIT margin rose by 330 basis points from the previous quarter, while Motion improved by 100 basis points.
This recovery suggests that pricing action is beginning to offset higher input and transportation costs. Additional benefits could come from operating leverage, efficiency programmes and disciplined capacity expansion. Even so, current margins remain below the peaks recorded between CY23 and CY25, leaving room for further normalisation.
Growth forecasts raised
CY27 and CY28 estimates have been increased by 6% and 7%, respectively, reflecting robust order intake and improved pricing. From CY26 through CY28, revenue is projected to record a compound annual growth rate of 23%. EBITDA and profit after tax are forecast to grow at annualised rates of 32% and 31%, respectively.
EBITDA margin is estimated at 13.9% in CY26, 15.2% in CY27 and 16.2% in CY28. The expanding backlog should help support these projections while providing resilience against short-term fluctuations in individual end markets.
Valuation and investment view
At a market price of Rs.7,045, ABB India was valued at approximately 63 times estimated CY27 earnings and 51.7 times CY28 earnings. The Rs.8,200 target is based on a multiple of 60 times projected December 2028 earnings.
The more positive view rests on three factors: consistently strong order inflows, expectations of faster revenue growth and evidence that the recent margin decline has bottomed out. The shares had also fallen around 11% from their annual high, creating a more favourable entry point despite the company’s premium valuation.
Risks to the outlook
Potential challenges include weaker order intake, aggressive competition, pricing pressure and renewed supply-chain disruption. Commodity inflation, currency volatility and geopolitical uncertainty could also delay the expected margin recovery. Any slowdown in industrial capital expenditure, data-centre construction, grid investment or renewable energy projects would pose an additional risk to growth assumptions.


Leave a Reply